Build your company faster, better and bigger than you ever could the way it is today.
Every company grows by pulling the same four levers: capital, talent, opportunities and acquisitions. We help growth-minded founders and owners pull all four harder, and make them feed each other, using a playbook most never consider. You stay in control.
Start with one question
Name three things you would do in the next 36 months that you can't do today, and say why you can't.
If every answer is “more money,” you need a financing, not this playbook. If your answers are about who you could hire, who you could partner with, who you could buy and who would finally take you seriously, keep reading. Those are exactly the constraints this playbook removes.
The four levers that drive growth
Every growing company, in every industry, grows by pulling some combination of four levers:
Capital
Money to invest ahead of revenue: new locations, products, people and markets.
Talent
Leaders, operators, advisers and directors whose experience and relationships change what the company can do.
Opportunities
Customers, partners, distributors and lenders willing to bet on you.
Acquisitions
Businesses that add customers, capabilities and earnings faster than you could build them.
When the levers feed each other, growth compounds
Pulled one at a time, each lever helps. Pulled together, they feed each other:
- Capital funds a hire, a partnership or an acquisition.
- Scale and a track record follow, and you can show you did what you said you'd do.
- Better people join, because there's more to be part of.
- Better opportunities arrive through the relationships and credibility those people bring.
- Better terms come on your next round of capital, and the loop starts again from a stronger position.
Each lap makes the next one easier. That's the difference between a company that grows and a company that compounds.
Why the flywheel stalls in a private company
A private company can only buy things with cash, and strangers can't check it. That caps every lever:
Capital comes slowly and costs a lot
Growth waits for profits, for a bank loan with your personal guarantee on it, or for investors who price in the fact that they can't sell for years.
Talent can't value what you offer
Private equity has no price and no market, so the people who could change your company mostly discount it to nothing.
Opportunities stall
Larger customers, partners and lenders can't verify a private company, so conversations that should move forward quietly stop.
Acquisitions go to someone else
Without the capital, a team to run what you buy, or a currency sellers can value, buyers with deeper pockets win the deal.
None of that is a talent problem. It's a toolkit problem.
How a public company gets more out of every lever
Becoming a public company gives your equity a price and a market, and makes your company something a stranger can verify. Those two changes strengthen every lever, and every opportunity you're already chasing becomes easier to win.
Capital
Investors can see a price, read audited numbers and eventually sell, so capital gets easier and cheaper to raise over time. Lenders can finally underwrite you. You stop asking “can we afford this?” and start asking “is this the best use of our capital?”
One founder set out to raise $1 million. When he listed the people he knew and what each might invest, the total came to less. After preparation, he raised more than $3 million.
Talent
Offer stock with a market value, not a promise. Leaders who'd never join a private company take the call. So do the people who never appear on an org chart: industry veterans for your advisory board, independent directors, consultants, referral sources and partners, all with a real reason to care about your success. In most industries your competitors are private, so you're the only one who can make that offer.
One founder had spent months trying to hire a president who wanted a share of the company. A week after he committed to going public, the same candidate accepted options at a fixed price, on the same salary and bonus.
Opportunities
Audited financials and public reporting let a stranger verify you without asking your permission. Partners, lenders and suppliers can check a public company without asking. The financials are already on file. At a lending fund where our founder was an executive, the best terms it had given went to a publicly listed borrower, for that reason.
Acquisitions
The other three levers are what make buying easier. Capital and lenders fund the cash part of a deal. The people you've attracted can integrate and run what you buy. And the credibility of public reporting means sellers, and the brokers who represent them, start calling you. Stock adds one more option: owners ready to sell will often take shares they can price and sell over time, alongside cash. Because private businesses usually sell for a modest multiple of EBITDA and public companies are often valued higher, a careful deal can add more value than it costs.
Because each lever is stronger, the flywheel turns faster. Every hire, deal and partnership is on the public record, which makes the next one easier and the next round of capital cheaper.
Two honest caveats. The first lap is the slowest and most expensive, and most companies spend their first year as a public company behind where they'd have been privately. And the flywheel runs in both directions: careless acquisitions and broken promises compound too. What decides the direction isn't the market. It's disciplined decisions, made repeatedly, for years. That's where we come in.
Same company, two paths
Picture two identical copies of a business with $1.5 million in revenue and $225,000 in EBITDA, growing 12% a year. One stays private. The other goes public within a year and uses the playbook. After five years:
Stays private
$2.6 million in revenue, no acquisitions, the founder owns 78%, a stake worth about $1.25 million, and none of it can be sold without selling the company.
Goes public and uses the playbook
$10 million in revenue, 3 acquisitions, the founder owns 45%, a stake worth about $10 million, and part of it can be sold.
A smaller share of a much larger company, worth roughly eight times as much.
This example assumes acquisitions at about 4 times EBITDA and a public valuation of 15 times EBITDA. In both copies the founder starts with 78% after early investors and an employee option pool; the public founder's share then falls as the company raises capital and issues stock for acquisitions. A company that lists and then doesn't use the structure ends up worse off than the private one.
From a $3.5 million listing to a $240 million sale.
Over the next seven years he made three acquisitions as a public company. One added technology. One did not work, and he closed it. The third took hold. He sold the original business, put the proceeds behind the one that was working, moved the company up to Nasdaq, and sold it for $240 million in cash.
The business that sold was not the business that went public. The listing is what let him buy his way into it. It is the best outcome we have seen, not a typical one.
revenue when the company went public
starting valuation
growing as a public company
all-cash acquisition
Every path to public, planned around you
There are three ways to become a public company. We've done all three: 11 direct listings, 4 reverse mergers and 2 IPOs.
Direct listing
You register your shares and they begin trading, usually on the OTC market, with the option to move up to a larger exchange later. No investment bank is needed, and the outcome depends on meeting published requirements, not on someone choosing you. Typically 9 to 10 months once the capital is in place.
Reverse merger
Your company merges into an existing public company. It's the fastest route, typically 4 to 6 months, but you inherit that company's history, so careful diligence is essential.
IPO
An investment bank sells your shares to its clients, and you land on a senior exchange like Nasdaq or the NYSE. It raises money at listing, but a bank has to agree to take you on, and few will for smaller companies.
The right route depends on your stage, goals, timing, capital needs, the condition of your financial records, and what's available in the market. We plan the strategy and the path around you, not around a default.
Find your stage
The playbook is the same. Where you start changes what matters most.
Scaling Up
You've built a business, and you're not done. Get more access to capital, talent and partners, and become the consolidator in your industry instead of its target.
Building to Buy
Your growth plan runs through acquisitions. Get the capital, team and credibility that make sellers say yes, with stock as one more way to pay.
Building to Sell
You'd like to sell in the next several years, and you've got five more years of fight left in you. Build a much bigger company first, then sell it, or your shares, on your terms.
Starting Up
You're at the beginning: a new company, or one you haven't incorporated yet. Build with the capital access, talent and credibility of a public company from early on.
How it works
Four steps, in order. Every step is optional and agreed in writing before it starts. You can stop after any step and owe nothing further.
Plan: The Four Levers Program
Every engagement starts here. Four one-to-one working sessions and a written playbook built around your company: a straight verdict on whether going public belongs in your plan now, later or never; which route and which market; your first raise, outlined; and a 90-day action list. About 30 days. $10,000, fixed, and nothing owed after. Read about the program.
Raise
If the plan calls for a raise, we prepare the company and coach you through it: corporate structure, cap table, financial records, governance, the offering, investor materials, data room, compliance and an outreach plan. Then you run a private placement from your own network, sized to your next milestone at a valuation you can support. $15,000, fixed, with 90 days of support, and only if we both think you're ready.
List
With the capital and shareholders in place, we manage the process of becoming a public company by whichever route fits: a direct listing, a reverse merger or an IPO. We bring in and coordinate the auditors, securities lawyers and other specialists, and keep the whole sequence moving. A monthly fee plus equity, agreed in writing, so we do well only if you do.
Build
Once you're public, ongoing strategic advice whenever we're needed: acquisitions, hiring with stock, partnerships, capital strategy, investor communication, and moving up to a larger exchange when it makes sense. A monthly fee plus options. This is where most of the value gets created.
What it costs. The Four Levers Program is $10,000, fixed. Raise-Ready, if you go on to it, is $15,000, fixed. Listing and building are on a monthly fee plus equity, agreed in writing before each step starts.
Third-party costs are additional and paid directly to those providers: accounting, audit, legal, stock exchange, transfer agent and filing fees. We'll estimate them once we've seen your financials. As a guide, they typically run:
- Direct listing:$300,000 to $500,000
- Reverse merger:$400,000 to $600,000
- IPO:$600,000 or more, before underwriting commissions
You don't need this money sitting in the bank. In almost every case, the private placement in step two is structured so you and your team can raise capital from your personal and professional networks to cover these costs, often with growth capital on top, and sometimes capital for acquisitions too. Your own outlay is the plan and the preparation. The people who already know you pay for the rest.
If your raise falls short, you can stop there. You owe nothing further, and no equity has been issued to us.
What you should know before you contact us
The first step is a fixed fee. After that, we’re paid monthly plus equity
The Four Levers Program is $10,000 with nothing owed after. If you go on to list, we handle the strategy, advise you at every step, and coordinate your lawyers, auditors, transfer agent and other specialists, and we only do well if your company does well over years.
You raise the first capital yourself, from your own network
We prepare you. We have no investor list, we're not a broker-dealer, and we never contact investors on your behalf.
We'll tell you the truth on the first call
If going public isn't right for you, or for us, we'll say so then, not after a proposal.
Who you'd be working with
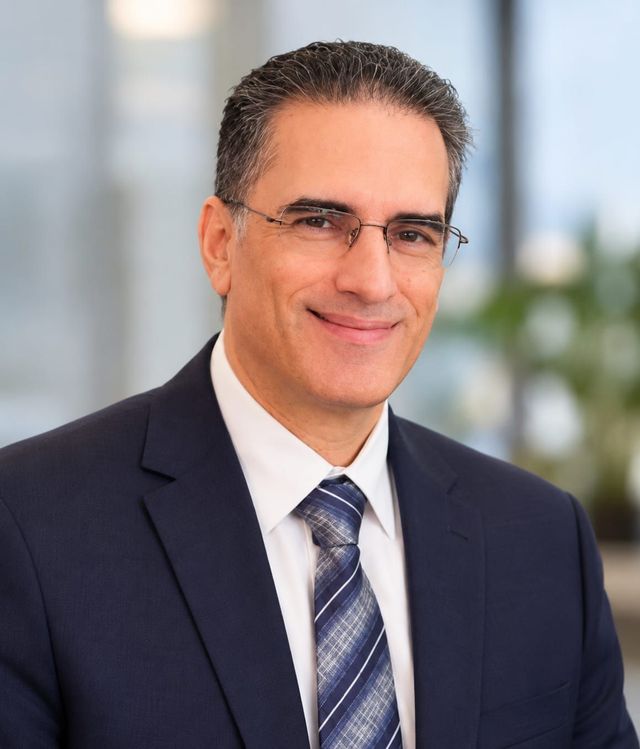
I'm Joel Arberman. I've spent more than 30 years in capital markets, across Wall Street, Bay Street and my own companies. I started as an equity analyst at asset management firms in New York, covering small and mid-cap companies. At 22 I became a partner at a 700-person investment bank, working out of its Toronto office as one of the first analysts anywhere to cover the internet as a sector. Most of my time went to the banking side: valuing companies, finding deals, and helping early-stage companies raise capital and go public. That's where I learned to tell which companies would work and which wouldn't.
Then I did it myself. In 1999 I took my own company public, writing the registration statement myself because nobody would help a company that small. Once our shares traded, things changed fast. A development firm took half its fee in stock. A PR agency took its entire fee in stock. A well-known venture capitalist joined our board for options. And we bought another company entirely with stock. I'd gone public to raise money. What I got was a massive growth advantage.
Since then I've taken 17 companies public through direct listings, reverse mergers and IPOs, several of them my own. I've sat in the founder's chair and stood beside it, and I've had hundreds of conversations with founders about whether they should do this. Often the honest answer is no. When it's yes, I stay with you through the building years, because that's where the value is created.
Ready to build something bigger? Let's see if this is your path.
Tell us where you are, and we'll set up a first conversation to pressure-test the idea for your company. No cost, no obligation. Not ready to talk yet? Ask for the free guide for your stage when you contact us.